Flight to Quality in Australian Offices: What It Means and How to Tell How Your Building Competes
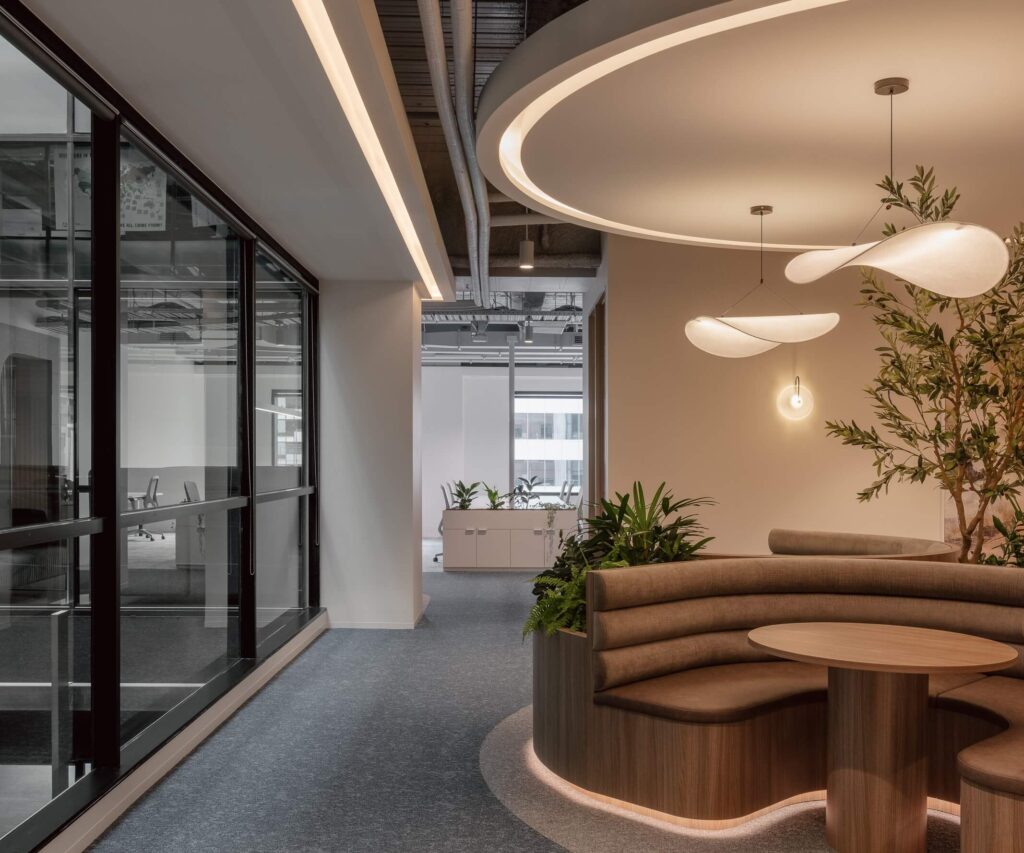
Australia’s office market is sending two signals at once. National vacancy reached 16.1% in July 2026, yet vacancy in Premium CBD buildings fell to 10.2%. For property owners, the difference highlights a growing challenge: understanding whether their building can compete for the tenants who are still making leasing decisions.
Flight to quality describes the shift towards higher-quality office accommodation in preferred locations, as occupiers prioritise the environment and amenities their people need. It helps explain why vacancy can rise across the broader market while demand strengthens for selected buildings. New supply, changing space requirements and the performance of older stock all contribute to the gap.
What Australia’s Office Vacancy Rate Reveals About Flight to Quality
The Property Council of Australia’s July 2026 Office Market Report recorded national office vacancy of 16.1%, up from 15.8% in January. CBD vacancy increased only slightly, from 14.8% to 14.9%, while Premium CBD vacancy fell by 1.2 percentage points to 10.2%.
The difference reflects the uneven distribution of demand. CBD markets collectively recorded positive net absorption over the first half of 2026, meaning occupied space increased. However, this strength did not extend across every grade or location, leaving some buildings with more space to lease even as others attracted tenants.
There are signs of continued leasing interest. CBRE reported a 19% year-on-year increase in Australian office enquiry volumes during the first half of 2026. Enquiry does not guarantee a completed deal, but it suggests occupiers continue to assess their options and commit to new premises where the offer meets their needs.
For landlords, the important question is how their buildings compare with the alternatives tenants can access. Wider trends in commercial office leasing provide further context on the priorities shaping tenant decisions, from budget constraints to demand for functional, collaborative workplaces.
What is a Premium Grade Office Building, and Does Grade Still Matter?
The Property Council of Australia uses a voluntary framework to classify office buildings as Premium, A, B, C or D grade, based on criteria that influence building quality. These include presentation, configuration, building services, environmental performance, lifts and amenities. Premium and A Grade are generally considered prime stock, while B, C and D Grade sit within the secondary category.
The framework provides a useful starting point for comparing buildings, but the grade alone cannot explain leasing performance. The PCA’s Guide to Office Building Quality recognises a broad range of factors that contribute to quality; the commercial outcome also depends on location, rental terms, competing supply and the needs of prospective occupiers.
Melbourne illustrates the distinction. Despite recording positive net absorption across A Grade offices, the city retained Australia’s highest CBD vacancy rate at 18.9% in July. New prime developments added substantial space to the market, creating more available stock even as tenants took up new accommodation.
Building quality is only one part of the equation. Understanding how occupiers define workplace value can help explain why some properties attract stronger demand, particularly when tenants weigh the quality of their working environment against the cost of occupying it.
For owners, a building’s grade establishes a benchmark, while its leasing performance reveals how well its offer meets current market expectations. Landlords need to understand both before deciding where to invest.
Australian Office Vacancy Rates: Brisbane, Sydney, Melbourne and Adelaide
National figures provide useful context, but local conditions determine how individual buildings compete. The July 2026 PCA figures show four different market conditions, each with implications for landlords.
Brisbane: Strong demand and fewer options
Brisbane CBD vacancy fell to 10.2%, the lowest rate among Australia’s CBD markets. Net absorption reached 38,785 sqm over the first half of 2026, despite new office space opening at 205 North Quay and 360 Queen Street. The Property Council’s Brisbane update points to sustained demand for quality accommodation.
For landlords, a tighter market can improve leasing prospects, although it also raises the stakes for buildings that fail to meet tenant expectations. Owners considering office fitouts in Brisbane need to understand how their building’s location, amenity and available space compare with competing properties.
Sydney: Premium buildings lead leasing demand
Sydney CBD vacancy fell to 13.3%, with Premium vacancy dropping from 8.9% to 7.7%. The PCA’s Sydney market update attributes the improvement to positive demand and limited new supply during the period.
The premium market is attracting tenants, but that does not guarantee every building will benefit. Location, flexibility, amenity and the quality of the available space all influence which properties make a tenant’s shortlist. For owners assessing office fitouts in Sydney, these factors can help identify where an upgrade may strengthen the building’s offer.
Melbourne: New supply complicates the recovery
Melbourne CBD vacancy eased marginally from 19% to 18.9%, remaining the highest nationally. The city absorbed more than 76,000 sqm of new office space while vacancy remained broadly stable, according to the PCA’s Melbourne update.
The result shows that leasing demand can coexist with elevated vacancy when new space enters the market. Owners need to consider how their buildings compare with new developments, particularly when tenants can weigh the benefits of a modern workplace against the cost of upgrading an existing one. Businesses and landlords exploring office fitouts in Melbourne should consider how design, functionality and building amenity can support their leasing objectives.
Adelaide: Demand and available space remain misaligned
Adelaide CBD vacancy rose to 16.3% in July, while net absorption reached negative 9,224 sqm over the first half of 2026. CBRE’s Adelaide figures also recorded office enquiry volumes of approximately 90,000 sqm during Q2, up 35% year-on-year.
The contrast between enquiry and negative absorption highlights why interest alone does not guarantee occupancy. Owners need to assess whether their space, commercial terms and building offer align with the requirements coming to market. For those considering office fitouts in Adelaide, understanding those requirements is a useful starting point for prioritising investment.
Will Lower Office Supply Reduce Vacancy in Australia?
Office development is slowing, which could ease competition over time. The PCA reported 176,303 sqm of new office space completed nationally in the first half of 2026, the lowest half-year total since July 2017. A further 167,171 sqm was expected in the second half, according to reporting on the July market results.
CBRE expects national CBD vacancy to tighten over the coming years, with future supply expected to sit well below long-term averages.
However, a smaller development pipeline will not resolve every building’s leasing challenges. Existing vacancy, tenant demand and the availability of competitive alternatives will continue to shape outcomes. Owners who understand their building’s position now will be better equipped to assess the investment required to remain competitive.
Want to understand which upgrades can improve leasing prospects?
Five Signs Your Office Building May Be Losing Competitiveness
Leasing performance offers useful evidence of how the market values a building. Extended vacancies on well-located floors, particularly when comparable properties lease more quickly, warrant closer investigation.
Feedback from tenant representatives can reveal where the offer falls short. If inspections repeatedly end without a second conversation, ask whether the floorplate, lobby, amenities, building services or available fitout match what prospective tenants are seeking.
Rising incentives can also signal pressure. If landlords must offer increasingly generous terms to secure tenants, the building’s effective rental performance may be weakening even when face rents appear stable. These patterns reflect wider shifts in commercial office leasing.
Renewals deserve the same scrutiny. Tenants seeking shorter commitments, smaller footprints or substantial refurbishment contributions may be responding to changing business needs, concerns about the building or a stronger alternative elsewhere. The reasons matter before an owner commits capital.
Finally, compare leasing outcomes across your own building. If recently refurbished floors consistently attract tenants while older floors remain vacant, the difference offers a starting point for identifying where investment could make the greatest commercial impact.
How Landlords Can Respond to the Flight to Quality
The right response depends on the building’s condition, location, tenant profile and investment outlook. Some owners may benefit from improving arrival areas and shared amenities; others may need to consider speculative fitouts, building services or a broader repositioning strategy. Where demand cannot support the required investment, owners may need to assess alternative uses.
The challenge is choosing where to invest and in what order. An upgrade should respond to a clear market need and a credible business case, rather than relying on the assumption that any improvement will attract tenants.
PMG’s guide, Building Value: A Landlord’s Playbook for Amenity Investment, explores seven investment levers, investment tiers and a framework for evaluating amenity decisions. Download the guide to assess your options and plan your next investment with greater confidence.